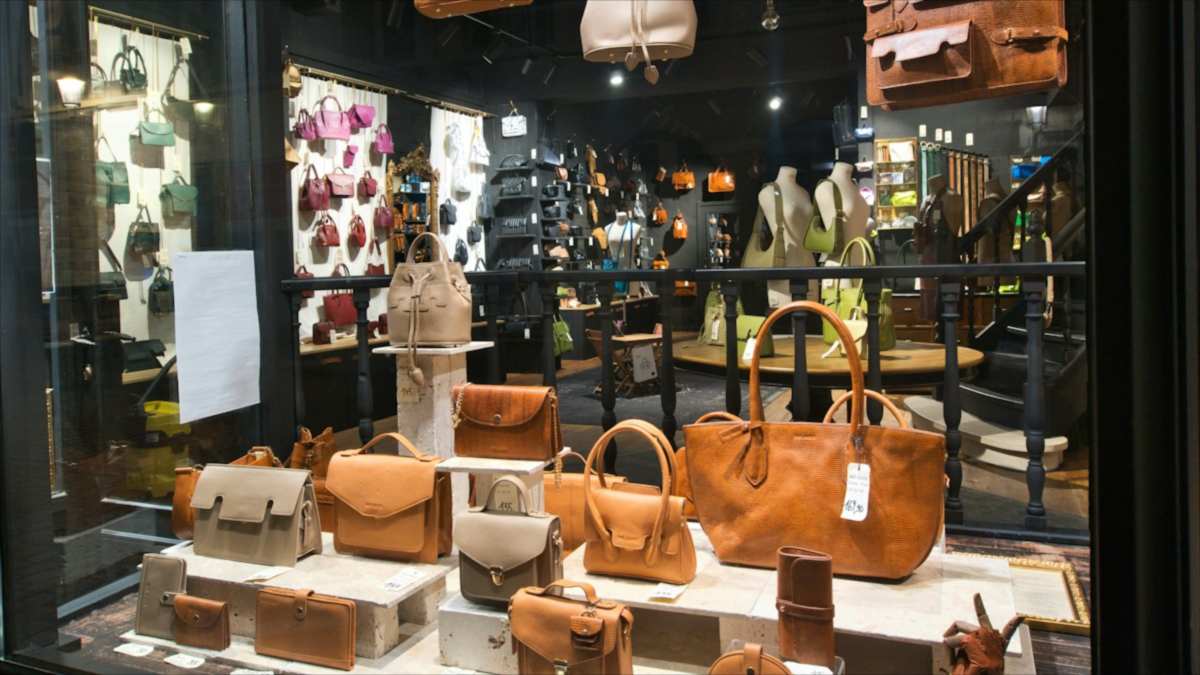
You are standing at a boutique counter, or more likely scrolling one on your phone, looking at a bag you nearly bought three years ago. Same leather, same clasp, same shape.
The price, though, has climbed so far that the bag now feels less like a treat and more like a test you are not sure you want to pass.
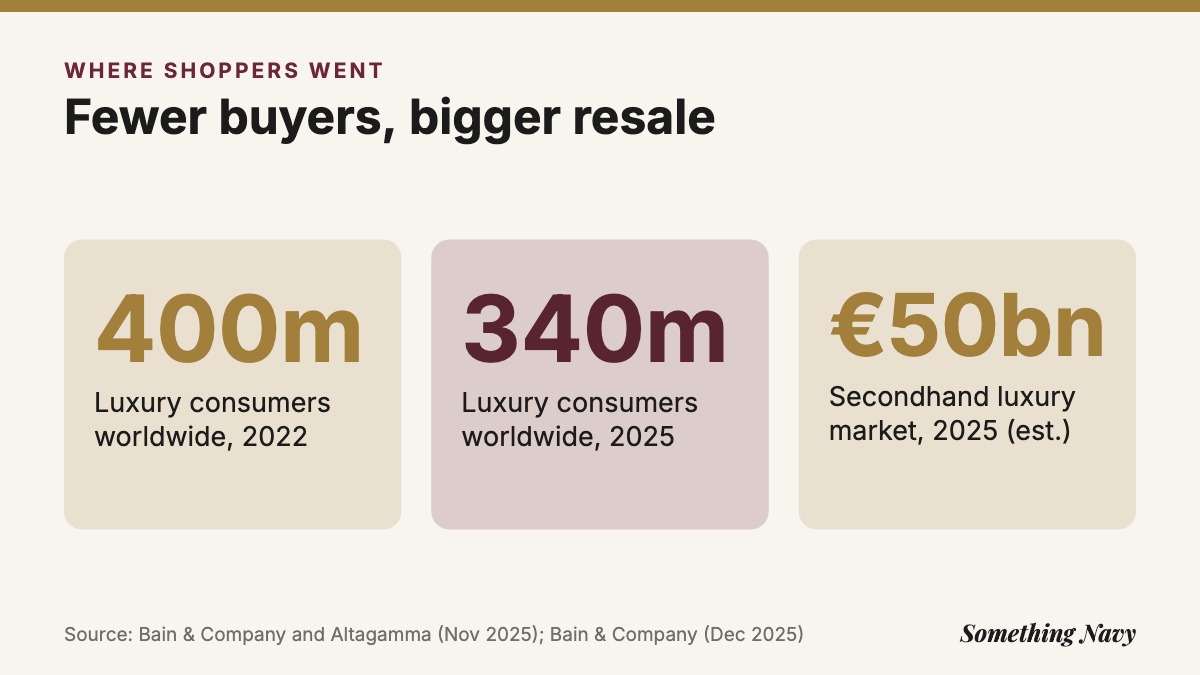
If that moment feels familiar, you are in very large company. Bain & Company and the Italian luxury association Altagamma, whose annual study is the industry’s yardstick, estimated in November 2025 that the number of luxury consumers worldwide fell from 400 million in 2022 to around 340 million in 2025.
Roughly 60 million people stepped back from the counter.
Where they went, and who stayed, says a great deal about the future of luxury fashion brands. It also says something about us: why we want expensive things in the first place, and what we are really buying when we pay for a logo.
A business built on a beautiful paradox
In 1899 the economist Thorstein Veblen published The Theory of the Leisure Class, the book that gave us the phrase “conspicuous consumption”. His point was simple and a little cruel: some goods are valued partly because they are expensive, since being seen to afford them is the point.
Economists now call these Veblen goods. For most products, a higher price means fewer buyers. For a Veblen good, a higher price can make the item more desirable, at least for a while, because it filters out the crowd.
Luxury houses have leaned on that logic for more than a century. The last few years showed what happens when they lean too hard.
1. The price ceiling has finally been reached
Between 2019 and 2023, luxury looked unstoppable. Look closer at the numbers, though, and much of that growth was not more people buying more things. It was the same things costing more.
McKinsey’s State of Luxury report, published in January 2025, found that price increases accounted for more than 80% of the sector’s growth over that period, while volume gains were more moderate. Its verdict was blunt: prices had reached a ceiling, and the higher prices were now hurting demand from aspirational shoppers.
Bain’s November 2025 study used even sharper language, describing a “broken price–value equation”. In plain terms, enough customers looked at the tag, looked at the product and decided the two no longer matched.
It has not even been a great deal for the brands. Bain notes that operating (EBIT) margins for a selection of personal luxury brands peaked at 23% in 2012 and have been squeezed since, as costs rose and there was less and less room left for further price increases.
The Veblen effect has a limit. Price can signal status, but only if people still believe the thing underneath is worth something.
The market totals tell the story. Bain and Altagamma put the global personal luxury goods market (clothes, bags, shoes, jewellery, watches and beauty) at €369 billion in 2023 and €364 billion in 2024, with a forecast of €358 billion for 2025. That 2025 figure is down about 2% at current exchange rates and flat at constant ones.
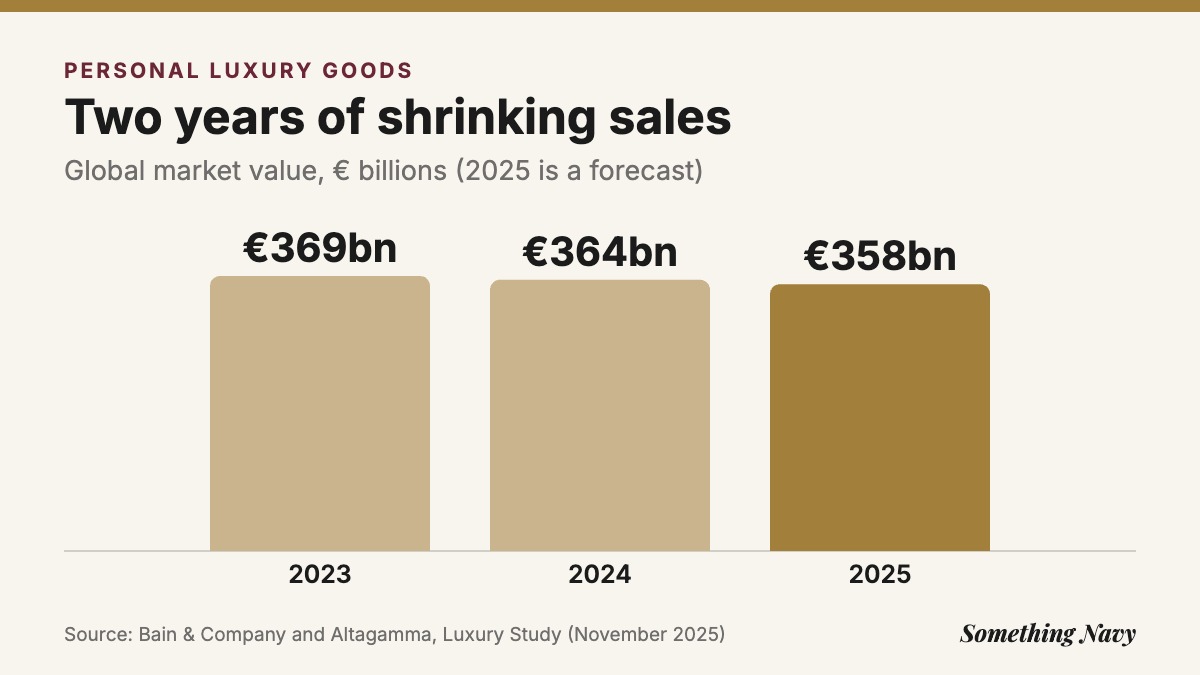
That is not a collapse. Total luxury spending, including travel, dining and cars, was estimated at €1.44 trillion in 2025 and broadly flat. But for an industry used to steady growth, two years of shrinkage in personal goods is a jolt.
2. The aspirational shopper is quietly walking away
Luxury has always relied on two very different customers. One is the very rich client who buys many pieces a year. The other is the aspirational buyer: the nurse, the teacher, the young lawyer who saves for one special bag or a pair of shoes for a milestone birthday.
It is the second group that has thinned out. Bain estimates that active luxury shoppers made up about 60% of the total addressable customer base in 2022, but only some 40–45% in 2025. Acquisition of new customers fell 5% between 2024 and 2025.
Meanwhile the wealthiest buyers kept spending. Bain says ultra-wealthy clients continued to sustain demand at the top, while aspirational consumers pulled back.
That matters for the future, because today’s aspirational buyer is tomorrow’s loyal client. A brand that prices out the 28-year-old saving for her first designer piece may find, a decade later, that she never came back.
Price can signal status, but only while people still believe the thing underneath is worth it.
Psychologically, the aspirational shopper was always paying for more than leather. She was buying a feeling of arrival, a small proof to herself that she belonged. Our clothes do shape how we feel and act (the idea behind enclothed cognition), so that feeling is not trivial. But when the price of arrival keeps rising, the emotional maths stops working.
3. Quiet is now the loudest signal
Here is the twist. Even among people who can afford luxury, the loudest logos have never been the most prestigious.
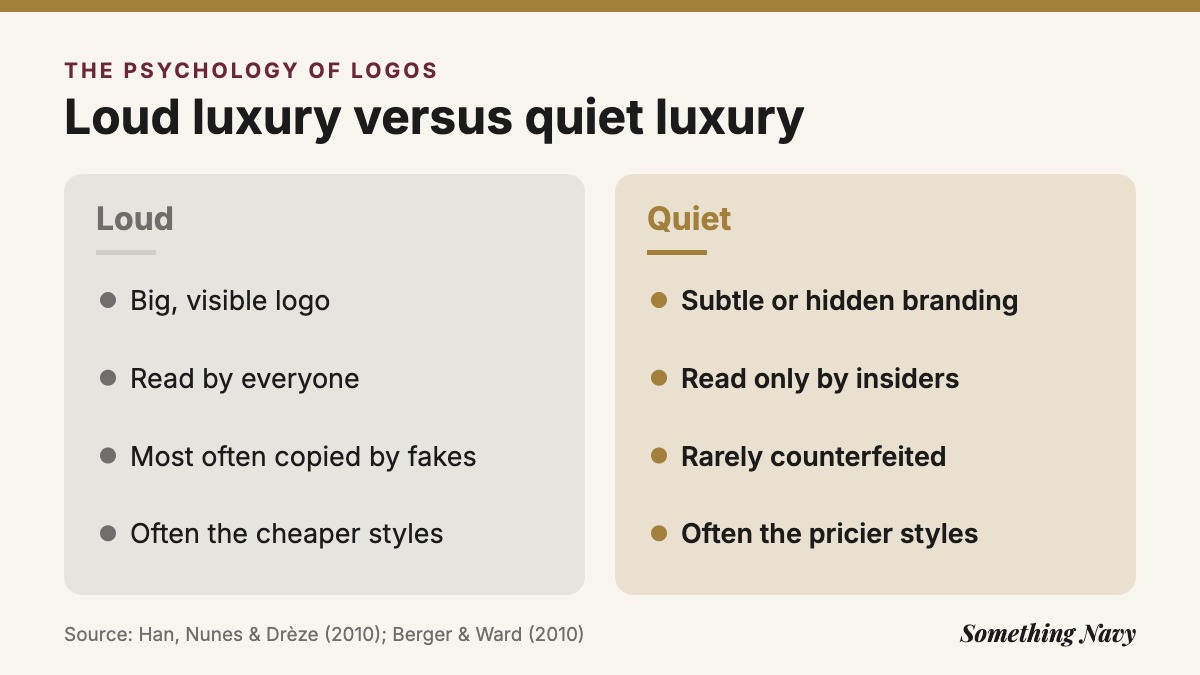
In a 2010 study in the Journal of Marketing, Young Jee Han and Joseph Nunes of the University of Southern California and Xavier Drèze of UCLA collected 465 Louis Vuitton and Gucci handbags from the brands’ own websites in 2008. Trained judges rated each bag from “quiet” to “loud”, depending on how prominently it displayed the brand.
The quieter the bag, the more it tended to cost. For Gucci, the gap between the quietest and loudest designs worked out at roughly $856. Counterfeiters, meanwhile, overwhelmingly copied the loud styles.
The researchers sorted shoppers into groups. Wealthy “patricians” with little need for status preferred quiet goods that only other insiders would recognise. Wealthy “parvenus” wanted loud ones to separate themselves from people with less money. “Poseurs”, who wanted status without the means, were the likeliest to consider fakes.
The same year, Jonah Berger of Wharton and Morgan Ward of the University of Texas at Austin published “Subtle Signals of Inconspicuous Consumption” in the Journal of Consumer Research. In one study, 48 female undergraduates at the University of Texas compared pairs of high-end handbags. Fashion students preferred the subtly branded bags more than other students did, and the difference was explained by their desire to stand apart from the mainstream.
Before running their experiments, Berger and Ward looked at 110 handbags on sale at Macy’s, Nordstrom and Saks, priced from $5 to $9,590. Logos were most explicit on bags costing around $200 to $300, then faded on bags over $600, which were about as discreet as the very cheapest ones. Past a certain price, the brand stopped introducing itself.
Another study, with 112 women recruited online and through fashion discussion boards, showed that knowledgeable shoppers chose subtler bags when they imagined using them in public, not in private. A quiet signal, the authors argued, works like a secret handshake. Outsiders miss it. Insiders read it instantly.
A word of caution. These were modest samples, mostly young American women and handbag prices from 2008, and preferring something in a survey is not the same as buying it. But the pattern has held up well as an explanation of why “quiet luxury” keeps returning whenever the market wobbles.
Real taste whispers. A logo, after all, is a signal anyone can copy.
4. The second life of a handbag
If the first-hand price feels out of reach, the second-hand market is waiting. And it keeps growing while new sales stall.
Bain estimated in January 2025 that the secondhand luxury goods market reached about €48 billion in 2024, with sales up 7% at current exchange rates, outpacing new luxury goods. Its December 2025 report put the 2025 figure at an estimated €50 billion, rising 4% to 6%, as tariffs and retail prices pushed some consumers towards pre-owned pieces.
At the November 2024 presentation of the Altagamma study in Milan, Bain partner Claudia D’Arpizio noted that shoppers could find almost the same products for about 45% less on resale sites.
Resale changes the psychology of ownership. A bag bought second-hand still carries the craftsmanship and the quiet signal, without the sense of being overcharged. It also suits a growing wish to buy fewer, better things, the same instinct behind building a capsule wardrobe.
For brands, this is both threat and opportunity. Every pre-owned sale is a new sale they did not make. But a healthy resale price also proves that the original was worth buying, which is exactly the reassurance a sceptical customer needs.
5. Meaning is replacing markup
The final force is generational. Bain describes Gen Z as more engaged with luxury but also more critical, more open and less loyal. It says this group judges brands on cultural relevance, not status.
That is a subtle but real change. Veblen’s shopper wanted to be seen to pay. A growing share of younger shoppers want to be seen to choose well, to know the story, the maker or the craft behind a piece. Interest in heritage and handcrafted styles fits this pattern.
Bain’s 2025 figures also show where spending is going instead. Money is shifting to experiences, affordable alternatives and resale. Accessible luxury fashion is rebounding, and outlets outperformed full-price stores in 2025. Jewellery was one of the strongest categories, forecast to grow 4% to 6%.
Geography is shifting too. Bain expected mainland China to shrink by 3% to 5% in 2025, while the Middle East grew by a similar margin. Luxury’s next customer may not look, or live, like the last one.
So what comes next for luxury houses
Put the five forces together and a likely picture emerges. Nobody can forecast fashion with certainty, but the direction of the data is clear.
- Fewer price hikes, more justification. Brands will have to show where the money goes: materials, craftsmanship, repairs, service.
- Softer logos. As the research suggests, quiet design protects against copying and appeals to confident buyers.
- Official resale and repair. Expect more houses to certify, buy back or restore their own pieces, to capture the pre-owned shopper.
- Courting the aspirational buyer again. Entry pieces that feel worth the money, rather than simply cheaper.
Bain itself still expects personal luxury goods to grow 4% to 6% a year over the next decade, reaching €525 billion to €625 billion by 2035. Its own wording is cautious: that is described as a realistic path, not a guarantee. The industry is not dying. It is being asked to earn its prices again.
How to shop luxury with a clear head
You do not need to run a fashion house to benefit from all this. The same psychology can protect your wallet.
Try this before you buy
- Name the signal. Ask who the piece is for. If the answer is “people who will notice the logo”, wait a week.
- Check the resale price first. If the same item sells for far less pre-owned, the new price is mostly paying for the shop.
- Work out the cost per wear. A well-made basic worn 200 times can beat a statement piece worn twice.
- Buy for the quiet details. Construction, fabric and fit last longer than any trend in logos.
It also helps to remember that a price tag is a poor guide to pleasure. If you want the wider picture, the research on money and happiness is a good place to start.
The quietest bag in the room
Think back to that bag on your screen. A century ago, Veblen would have said its price was the point. The research of the last fifteen years says something gentler: the people most at ease with luxury are often the ones who need it least to speak for them.
The brands that thrive next will be the ones that understand that. And the shoppers who thrive will be the ones who buy a thing because they love it, not because it shouts.
Sources
- Bain & Company & Altagamma. (2025, November 20). Global luxury stays resilient despite economic headwinds and shifting consumer trends that reshape market [Press release]. Link
- Bain & Company. (2025, January 17). Luxury in transition: Securing future growth. Link
- Bain & Company. (2025, December 18). Finding a new longevity for luxury. Link
- Berger, J., & Ward, M. (2010). Subtle signals of inconspicuous consumption. Journal of Consumer Research, 37(4), 555–569. DOI
- Han, Y. J., Nunes, J. C., & Drèze, X. (2010). Signaling status with luxury goods: The role of brand prominence. Journal of Marketing, 74(4), 15–30. DOI
- McKinsey & Company. (2025, January 13). The State of Luxury: How to navigate a slowdown. Link
- Veblen, T. (1899). The theory of the leisure class. Macmillan. Link
Updated 17 October 2026: we rewrote this article with new research, current figures and sources. Cover photo: Phillip Flores on Unsplash. Charts and graphics: Something Navy.
How we reported this. We went back to the original research for this story, 7 sources in all, listed above, and checked every figure against them. If you think we have got something wrong, tell us and we will look at it. Read more about how we work.